Is very downbeat. My notes are here.
Thursday, 6 February 2025
Monday, 3 February 2025
Intangibles and Industry Concentration
Very pleased to see this article. Why has industry concentration risen? Because of intangibles....
Intangibles and Industry Concentration: A Cross‐Country Analysis
"This paper presents new evidence on the growing scale of large businesses in the United States, Japan and 11 European countries. Itdocuments a broad increase in industry concentration across the majority of countries and sectors over the period 2002–2017. Therising concentration is strongly linked to investment in intangibles—particularly innovative assets; and software and data—andthis relationship is magnified in more globalised industries. The results are consistent with intangibles disproportionately bene-fiting large firms, enabling them to scale up and increase their market shares by leveraging intangibles across multiple markets."
Here's the key chart


Wednesday, 29 January 2025
UK Intangible investment: ONS data
1. The ONS has estimates of UK intangible investment 97-02 : Investment in intangible assets in the UK: 2022 with data here:
Investment in intangible assets in the UK.
2. if we start by industry we have:

Showing that these data are for what I call for short-hand the "business" sector, i.e. excluding L, real estate and O/P/Q, public admin, defence, health, educatoin.
3. to get a sense of scale, what is GVA for these sectors? the ONS Blue Book, 2024, industry analysis, has this graph

with the underlying data here. This gives totdal GVA= 2.265tr, Govt = 0.433tr, Real estate = 0.292tr => business sector = 1.539tr = 68% of total GVA (govt = 20%, real estate 13%).
4. Returning to intangibles we have in 2022: tangible investment = 167.3£m, intangible 199.7bn, of which £77bn is capitalised and £122 is not. That gives 5% capitalised intangible/GVA and 12% total/(GVA+uncapitalised).
5. the industry intangible intensities are below. ICT, Manufacturing, finance and the arts are intangible intensive.

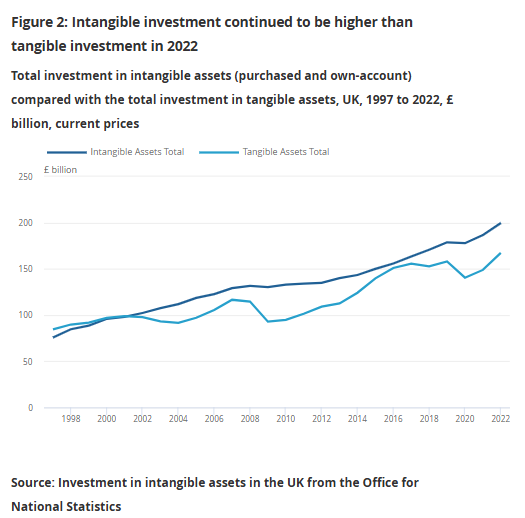
with the 2022 figures being 199/(1539+122) = 12% and 167/(1539 +122)=9%. (or for capitalised, 77/1539 = 5% and 167/1539 = 11%).
Building new infrastructure: getting a sense of scale
The Chancellor is going it seems to announce backing for new infrastructure today. For example, a new runway at Heathrow might cost £14bn (see Tim Leunig's excellent substack: https://timleunig.substack.com/p/how-to-fund-heathrows-expansion) . Is that a lot or a little?
1. the official ONS capital stock data are here: Dataset Capital stocks and fixed capital consumption and the publication using the data is here: Capital stocks and fixed capital consumption, UK:
2. Here are the data for 2023

Note to table: Some definitions are: “Other buildings consist of all buildings that are not dwellings and include commercial buildings, industrial buildings, and buildings used to provide public services (for example, schools and hospitals). Other structures include those that are not buildings; for example, transport (roads, railways, runways, ports), energy and communications infrastructure.” (https://www.ons.gov.uk/economy/nationalaccounts/uksectoraccounts/articles/improvingestimatesoflandunderlyingotherbuildingsandstructuresinthenationalbalancesheetuk/2022).
3. As the table shows
a. around 75% of the captial stock are buildings of various types.
b. the total value of the UK capital is 10,751 billion. If a third runway, which is a huge project, costs £14bn, that's an increase of 0.13% of our nation's capital stock.
Tuesday, 14 January 2025
The Creative Industries
I often struggle to remember who is in and out of the official definition of the creative industries. Here is the table:

And the source of all this is here: taken from the DCMS Sectors Economic Estimates Methodology
Thursday, 9 January 2025
India's growth success: log scales in action
In class we have spent a lot of time saying how informative log scales are. Here's a perfect illustration from Martin Wolf in the FT.
1. The main story is : An economically dynamic India is Manmohan Singh’s greatest legacy. He drove radical reform of an anti-market policy regime that was strangling growth. Link.
2. "Singh’s most important achievements as a policymaker were made during his years as finance minister from 1991 to 1996. "
2. How do we see that in the data? Notice the log scale allows us to read off the growth rate break from just that time.

4. and here by contrast is the data on a non-log scale: which fools you into thinking it's a post-2000 effect.

Saturday, 4 January 2025
Visual summary of our work on intangibles
If you'd like a beautiful visual summary of some of our work on intangibles, do look at this amazing graphic storyboard from The Beautiful Truth.
The magazine is at this link. The graphics are fantastic.
Tuesday, 17 December 2024
Public and private sector pay
As ever the IFS is brilliant on this, from a July 2024 paper, by Cribb and O'Brien.
1. The overall picture is lagging public sector pay since 2001.
"And taking the long view, real public sector pay at the end of 2023 was still 1% lower than its level at the beginning of 2007, almost 17 years earlier. Real private sector pay was only 4% higher over the same period."

2. Interestingly, public pay has varied an awful lot, with low paid public sector workers doing relatively well.

3. and different professions faring differently.

"Figure 6 shows how pay has changed for some major (and high-profile) public sector occupations: nurses, doctors, teachers and educational assistants compared with the public and private sectors as a whole.5 For comparability (particularly due to discontinuities in NHS England data), we focus on the period since 2010.
Figure 6 shows that pay for most of these high-profile public sector occupations has fallen by more since 2010 than the average for public sector wages. The one exception is educational assistants, a relatively lower-paid occupation, whose average pay grew significantly faster than even average pay in the private sector. That pay growth for teachers, doctors and nurses lagged behind the public sector average is not necessarily surprising due to the pay compression in the public sector documented in the previous section, as these are among the better-paid public sector occupations. The reductions in pay for teachers in the 2010s were particularly large and slightly larger than implied by pay scales, reflecting the fact that the teacher workforce has become slightly less experienced (and therefore less well paid) over time.6 This has happened in other occupations too; for example, there have been significant expansions in the number of doctors over time, leading to increases in the share of doctors who are younger and therefore less well paid (General Medical Council, 2023).
The labour market: December 2024 release
1. I have been worried for some time that the UK labour market has been impaired following the disruption from Covid and the like. To me, there is a risk that U* has risen to more than 4.5% the BoE has estimated (their estimate is on p. 13 of the November MPR).
2. So the labour market data will be crucial on this. What does it say? Fkigure 4 of the release shows a blip up
"Annual average regular earnings growth for the private sector was 5.4% in August to October 2024 (Figure 4). This was up on the previous three-month period (4.9%) and last higher in March to May 2024, when it was 5.6%."

3. What are we to make of this blip up? I don't want to read too much into one month, but it's concerning. The ONS does say "This growth rate is affected by a small decrease in the October 2023 estimates, which has caused a slight base effect.". It turns out that wages fell in October 23, so there is an effect here, but this is one month in a 3month on 3 month measure.
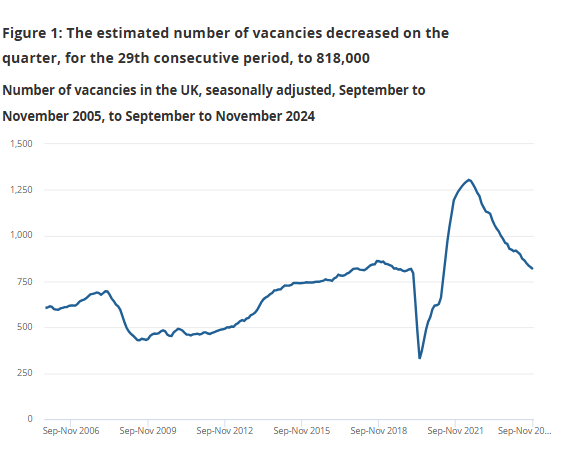
4. Vacancies have continued to fall, and are now roughly at the 2019Q4 pre-pandemic level. Our previous work, however, showed this was inflationary.

Wednesday, 13 November 2024
Adjustments along many margins
We have spent time in class reviewing how firms can adjust to prices by changing no only quantities, but other margins as well. Here's an example from the Next case
Para 396: "in the early 2000s paid rest breaks which sales consultants had received were removed following the introduction of the national minimum wage".
Subscribe to:
Posts (Atom)